- Promotions
Declaration of Source of Funds: When Is It Required and How Is It Completed?
Contents
1. What is a declaration of the origin of funds?
2. When is a declaration of the origin of funds required?
3. What thresholds trigger a check on the origin of funds?
4. Who might request this declaration from you?
5. What information does the declaration contain?
6. How do you complete a declaration of the origin of funds?
7. What happens if the declared information is false?
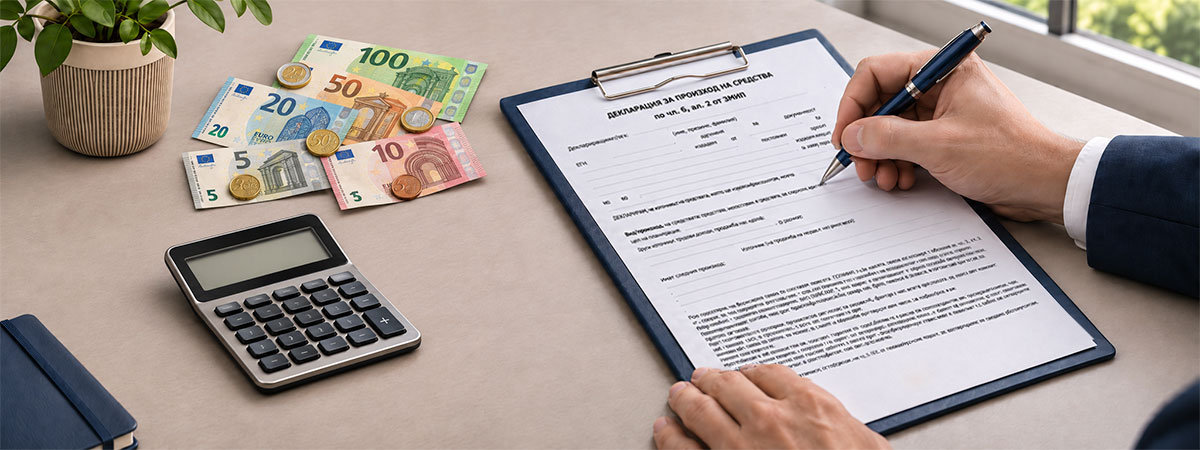
A declaration of the origin of funds is a document in which you specify the source of the money used for a particular transaction or financial operation. It may be requested by a bank, a notary, an insurer, or another "obliged entity" under the Measures Against Money Laundering Act (MAMLA). This most commonly occurs in cases involving large payments, real estate transactions, or the transfer of significant sums.
What is a declaration of the origin of funds?
This is an official document, as per Article 4, Paragraph 7 and Article 6, Paragraph 5, Item 3 of the Measures Against Money Laundering Act (MAMLA), in which you declare the lawful origin of the funds used for a specific financial operation [1]. Its purpose is to prevent the financial system from being used to conceal funds derived from criminal activity.
You bear legal responsibility for the information provided; therefore, the data must be accurate and truthful.
When is a declaration regarding the origin of funds required?
A declaration may be requested if a transaction exceeds a certain statutory threshold, or if the institution deems it necessary to further clarify the origin of the funds. Common scenarios include:
- real estate transactions (buying or selling), where the declaration under Article 66, Paragraph 2 of the AMLA (Law on Measures against Money Laundering) must be notarized;
- leasing or renting a property for a monthly fee of 10,000 EUR or more;
- depositing or withdrawing a large sum of cash at a bank;
- incorporating a company or increasing its capital through a cash contribution;
- transferring funds abroad exceeding a certain amount.
The specific requirements depend on the type of transaction and the surrounding circumstances.
According to the AMLA, comprehensive customer due diligence (including clarifying the origin of funds) is required for occasional transactions valued at or above the BGN equivalent of 15,000 EUR; for cash payments, this threshold is 5,000 EUR [1]. Furthermore, the Law on the Restriction of Cash Payments (LRCP) establishes a general threshold of 5,112.92 EUR (10,000 BGN) – for amounts exceeding this, payments within the country must be made via a bank account rather than in cash [2].
What thresholds trigger a check on the origin of funds?
For the sake of clarity, the main thresholds under current legislation are as follows:
| Basis | Threshold | Legal Act |
| Occasional transaction or deal | 15,000 EUR | AML/CFT Act, Art. 11 |
| Cash payment for an occasional transaction | 5,000 EUR | AML/CFT Act, Art. 11 |
| Transfer of funds | 1,000 EUR | AML/CFT Act, Art. 11 |
| Domestic payments | EUR 5,112.92 (BGN 10,000) | ZOPB, Art. 3 |
| Monthly property rent | EUR 10,000 | ZMIP, Art. 4 |
These thresholds may also apply to several related payments made on the same grounds. Therefore, splitting a larger sum into several smaller payments does not automatically mean that the legal requirements will not apply [2].
Who can request the declaration from you?
Individuals and institutions that have obligations under the ZMIP are referred to as “obliged entities.” Depending on the specific transaction, a declaration may be requested by:
- Banks and non-bank financial institutions. They may require information regarding the origin of funds for transactions that exceed certain value thresholds or are considered high-risk.
- Notaries. In the case of real estate transactions, a notary fulfills the obligations stipulated by the Law on Measures against Money Laundering (LMML).
- Investment intermediaries and insurers. Checks may be conducted in relation to specific investment and insurance products.
- Accounting and audit firms. They also fall within the category of "obliged entities" and, under certain circumstances, are required to implement the measures stipulated by the law.
- Certain merchants. This group may include merchants dealing in high-value goods, provided that the conditions specified by law are met.
Each of these entities assesses on a case-by-case basis whether a given transaction requires a declaration, based on risk factors and specific statutory thresholds.
What information does the declaration contain?
The content depends on whether the declaration is submitted by an individual (natural person) or a legal entity. For an individual, this typically includes their full name, Personal Identification Number (EGN), identity card details, and address. For a legal entity, it includes the company name, Unified Identification Code (EIK), registered office address, and details regarding the legal representative.
In both cases, the declaration must specify the amount involved, the subject of the transaction, and the specific source of the funds. This could be employment income, savings, an inheritance, a donation, a loan, or the sale of property.
How do you complete the declaration of origin of funds?
When filling out the form, it is advisable to provide information as accurately as possible. First, have your personal or company details ready. Next, specify the exact amount and the transaction to which the declaration relates.
Describe specifically where the funds come from. For instance, instead of simply stating "savings," you could indicate the time period and the source of the income from which those savings were accumulated. Finally, sign the declaration—either personally or through an authorized representative—and submit it to the institution that requested it.
If the origin of the funds cannot be clearly established based on the description alone, you may be required to provide additional documentation. This could include an employment contract, a bank statement, a deed of sale, or a certificate of inheritance. These documents help verify the source of funds stated in your declaration.
What happens if the declared information is false?
If you provide false or misleading information, the obligated entity may refuse to carry out the transaction and, where there are legal grounds to do so, may notify the competent authorities. Under certain circumstances, declaring false information can even lead to criminal liability.
The best approach is not to wait until the actual transaction takes place to find out what will be required of you. If you are planning a transaction involving a significant sum, check the requirements of the specific bank, notary, or other institution in advance, and prepare the documents that can prove the origin of the funds. This will help you avoid additional checks, last-minute requests for documentation, and potential delays to the transaction.
Sources
[1] Law on Measures against Money Laundering.
[2] Law on Limiting Cash Payments.